This is a US planning guide, checked 3 November 2026, rather than advice about your specific legal or tax situation. Other countries have different entities and rules. Use the questions below with your state filing office and, where needed, an attorney or tax professional who knows your activity and location.
Guides Karan Singh BhakuniUpdated 3 Nov 2026
Do I Need an LLC for My Blog? A US Decision Guide
Karan Singh BhakuniUpdated 3 Nov 2026- 10 min read
- 7 sections
- 3 comparison tables
- 8 questions answered
The short answer
You do not need an LLC simply to publish a blog in the United States. Whether forming one is appropriate depends on the activity, ownership, contracts, exposure and state rules. An LLC can separate certain business obligations from an owner, but it does not erase every personal liability or automatically reduce taxes. There is no universal blogging-income threshold that answers the question.
Want the site rather than the reading? Build one free with Grigora
Contents7 sections
Read nextDo I Need to Register My Blog as a Business? US Guide
1. Separate the business entity from the other registrations
Choosing a business structure is different from buying a domain or deciding whether a post earns money. An LLC is a legal entity created under state law. A person operating alone can also conduct business as a sole proprietor; that route does not create the same separation between the person and business. Multiple owners need a deliberate ownership and decision-making arrangement.
| Item | What it addresses |
|---|---|
| LLC formation | A state-law entity, ownership/governance and the liability rules that apply to it. |
| DBA or assumed-name filing | A name used for business under applicable local rules; it is not itself an LLC. |
| EIN | A federal tax identification number, with its own eligibility and reporting requirements. |
| Business license or permit | Permission for a particular activity/location where required. |
| Trademark and domain | Brand rights and a renewable website address are separate matters. |
Forming an LLC does not automatically register a trademark or grant exclusive rights to a blog name everywhere. Before committing to a name, check the relevant business-name and trademark issues as well as domain availability. See the SBA launch guidance for the distinctions; then use the responsible state and local offices for your actual requirements.
2. Ask what the LLC would and would not protect
Limited liability concerns particular obligations and applicable law. It is not a promise that every lawsuit stays away from your personal assets. For example, the State Bar of Texas entity guide explains that entity protection does not cover an individual’s own intentional torts or professional malpractice, and discusses exceptions to the separation. Ask a local attorney which limits apply to your work.
Read any personal guarantee or obligation you sign in your own name: it is a separate issue from merely owning an LLC. Also ask how to identify the contracting party and sign appropriately for the business. A new entity should not be assumed to cancel an old obligation or fix a claim about something you previously published.
- Publishing: review the actual wording, sources and permissions for allegations, advice, photographs and other people’s work.
- Commercial work: inspect sponsor deliverables, refund terms, products, paid services and any contractual promises.
- People and ownership: clarify co-owner authority, contributor rights, hiring and who owns the content, domain and accounts.
- Risk controls: consider suitable contracts, editorial checks, permissions, security and insurance as separate decisions. Ask an insurer what the actual policy covers and excludes.
Do not wait until the blog is generating significant revenue to examine those questions. A low-revenue publication can still make a harmful allegation, sign a contract or misuse a photograph. Equally, an income figure alone does not show that an LLC is the right choice. Evaluate what you do and what obligations you are taking on.
3. Understand default federal tax treatment
Legal separation under state law and federal tax classification are different questions. The IRS LLC guidance distinguishes the default treatment by ownership and the elections an eligible entity may make.
| Domestic LLC situation | Default federal income-tax treatment |
|---|---|
| One member | Generally disregarded as separate from its owner, unless a corporate election is made. |
| At least two members | Generally a partnership, unless a corporate election is made; special cases can apply. |
| Corporate or S-corporation treatment considered | Separate eligibility/election and compliance questions; not automatic on state formation. |
For an individual with a default single-member LLC carrying on a trade or business, the IRS single-member guidance says the activity is generally reported on the owner’s return and self-employment tax applies in the same manner as for a sole proprietor. Employment and certain excise taxes have separate treatment. Forming an LLC is therefore not, by itself, evidence of a lower tax bill.
For a tax comparison, ask a qualified professional to model your actual profit, owner compensation where relevant, filing/payroll work, state charges and eligibility. Compare the added costs with the proposed treatment. Avoid a universal “elect S-corp above this revenue” rule or a claim that an LLC reduces your chance of an audit. Neither replaces an analysis of your circumstances.
4. Build a state-specific first-year and ongoing cost record
A filing-service advertisement is not the complete cost of maintaining an entity. Open the official formation and tax pages for the state where you actually operate. If considering another state, ask whether registration and obligations would also apply where you live or conduct business; compare the combined responsibilities.
| Record separately | Questions for the official source or adviser |
|---|---|
| Formation | What is the current filing fee, required document, name rule and expected processing route? |
| Registered agent and address | Who qualifies, where must the agent be available, what becomes public, and is a paid service optional? |
| Recurring obligations | Which reports, taxes or fees apply; what dates and minimum amounts; who will submit them? |
| Operations | What records, banking, bookkeeping, contracts, licenses and appropriate insurance are needed? |
| Change or closure | What must be filed if ownership changes, the activity stops or the entity is canceled? |
State example, not a nationwide price: California’s Franchise Tax Board lists an $800 annual LLC tax for LLCs doing business or organized there, with specific exceptions and other possible obligations. It says the yearly tax remains due even without business activity until cancellation. Read the applicable exceptions and filing rules for your actual tax year; an expired first-year offer is not a blanket current exemption.
Copy the official amount, due date, source URL and checked date into your record, then add any chosen service quote separately. Distinguish an agent requirement from the decision to purchase an agent service. Check all public-record fields rather than assuming a paid agent makes every address private. Give each recurring task an owner and a reminder.
Also worth readingHow Much to Charge for a Blog Post: A Practical Quote Method
5. Make a decision from facts, not a revenue shortcut
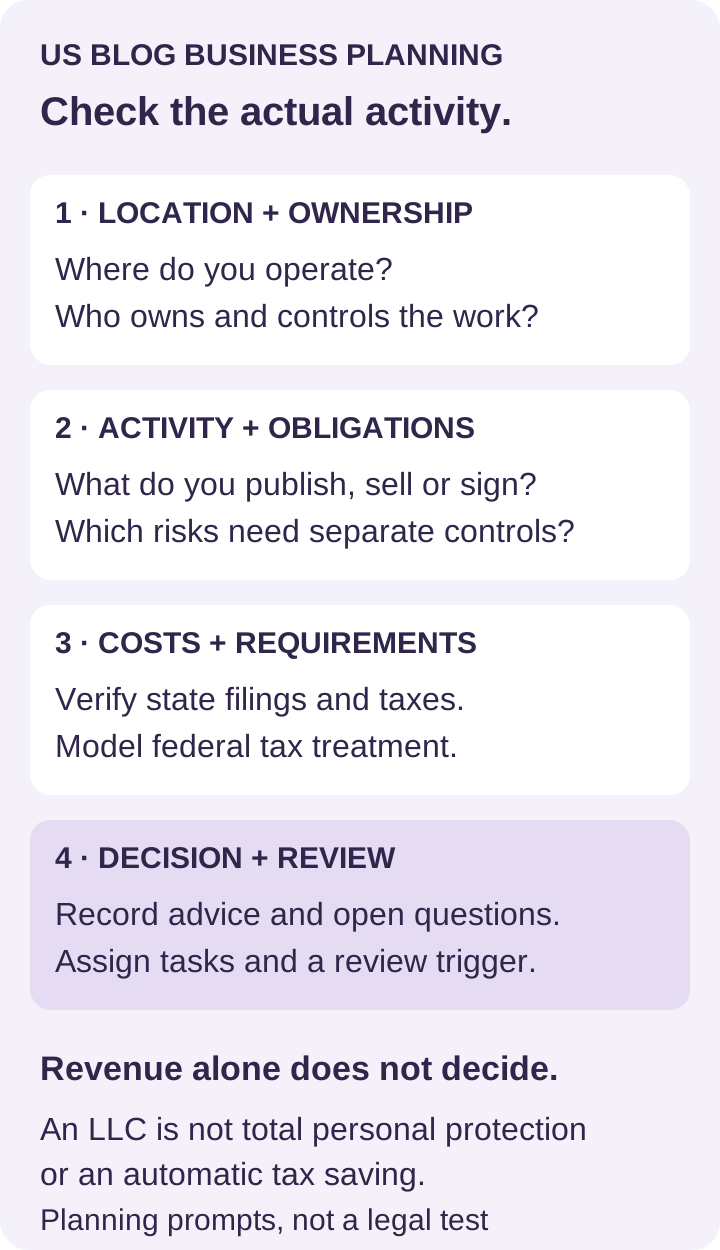
Prepare a short decision note: where the activity operates; who owns it; what is published, sold or promised; existing obligations; the risks a lawyer identifies; the actual first-year and recurring costs; and what would trigger another review. Record unresolved questions before buying a formation package.
- Illustrative personal journal: one writer, no products or planned contracts. Start by checking the publication’s actual risks and applicable local requirements; do not invent a mandatory LLC rule just because the journal is public.
- Illustrative paid guide: a writer is preparing a product and sponsor agreement. Review the content, permissions, consumer promises, contract party and suitable risk controls before launch; a small first payment does not settle the entity decision.
- Illustrative shared publication: two owners contribute money and articles. Clarify ownership, approval authority, exit arrangements and entity/tax options before treating the project as an informal single-owner blog.
These are invented decision examples, not client cases or evidence that an LLC protected someone in a dispute. They identify questions to investigate; they do not assign a legal outcome or tell every reader in that situation to choose the same structure.
6. If an LLC is the chosen route, plan the whole handover
- Verify the state filing route, name and agent/address requirements. Prepare an appropriate operating agreement and ownership arrangements.
- After state formation, check whether the LLC needs an EIN and which application method is available. Use the official IRS route.
- Confirm the bank’s document requirements and keep the business’s finances and records organized. Check how existing contracts, content rights, domain accounts and payments should be handled.
- Check separate DBA, license, tax and reporting obligations. Put required initial and recurring filings on a calendar with a named owner.
- Save formation approvals and governing documents, and review changes in activity, ownership, location or law. If closing, follow the relevant cancellation and final-return process.
An EIN obtained directly from the IRS is free; the IRS says to form an LLC with the state before applying. Not every default single-member LLC without employees or excise-tax liability needs its own EIN for federal tax purposes, although a bank or state requirement can make one necessary. Follow the IRS instructions for the taxpayer identification number used on a particular form.
Current federal reporting note: as checked 3 November 2026, FinCEN’s August 2026 final-rule notice says US-created companies are exempt from beneficial ownership information reporting to FinCEN. Certain foreign-created entities registered in the US may still have obligations. That federal exemption does not eliminate state reports, taxes or licenses. Check FinCEN directly before relying on older formation checklists or paying a BOI-filing solicitation.
Frequently asked questions
There is no general US LLC requirement just for publishing a blog. Your activities, location and other legal obligations still matter. Assess those separately from the technical act of publishing.
There is no universal blogging-revenue threshold that mandates this particular entity. Income reporting, licenses, contracts and the choice of entity are separate questions; verify the rules for your activity and location.
Do not assume that it will. Liability can depend on your own conduct, the claim, contracts, state law and other facts. An LLC is not a substitute for accurate publishing, permissions, suitable insurance or individualized legal advice.
No. Default single-member treatment often reports the activity on the owner’s return, and self-employment tax can still apply. Any different tax election needs an eligibility and cost analysis rather than a promise based on revenue alone.
Not in every situation. IRS single-member guidance describes an exception for a disregarded entity without employees or excise-tax liability, while bank or state requirements can still call for an EIN. Check the instructions for the actual application and reporting form.
An agent requirement and a paid service are different. Verify your state’s qualification, address and availability rules, and whether you or another eligible person can act. A service does not guarantee that every public filing field is private.
No. State entity-name registration, a domain, a DBA and trademark rights serve different purposes. Check for conflicts and the protection you actually need before committing to a name.
Not necessarily. Required reports or taxes can continue while the entity exists. Follow the relevant state cancellation, final-return and other closure requirements rather than assuming inactivity ends every obligation.
Practical writing on building a site, growing an audience and sending email people open. No more than one a week.

Karan Singh Bhakuni
118 articles on the Grigora blog
More on Guides
Guides
Do I Need to Register My Blog as a Business? US Guide
US registration depends on your location, name, ownership and activities. Separate forming an entity from DBA filings, licenses, tax accounts and income reporting, then use an official-source…
21 Nov 202313 min read
Guides
How Much to Charge for a Blog Post: A Practical Quote Method
Use current writing-rate benchmarks as context, estimate the complete job and send a clearly scoped quote. Includes a worked example, revision terms and a quote template.
25 Oct 202311 min read
Guides
Cost to Run a Blog: Renewals, Tools and a Yearly Budget
Plan the next year of an existing blog: record real renewal bills, separate included features from extras, account for usage and maintenance, and compare cash due with a monthly reserve. Includes an…
20 Oct 202310 min read